Using Your Bloomfield Hills Starter Home Equity to Move Up
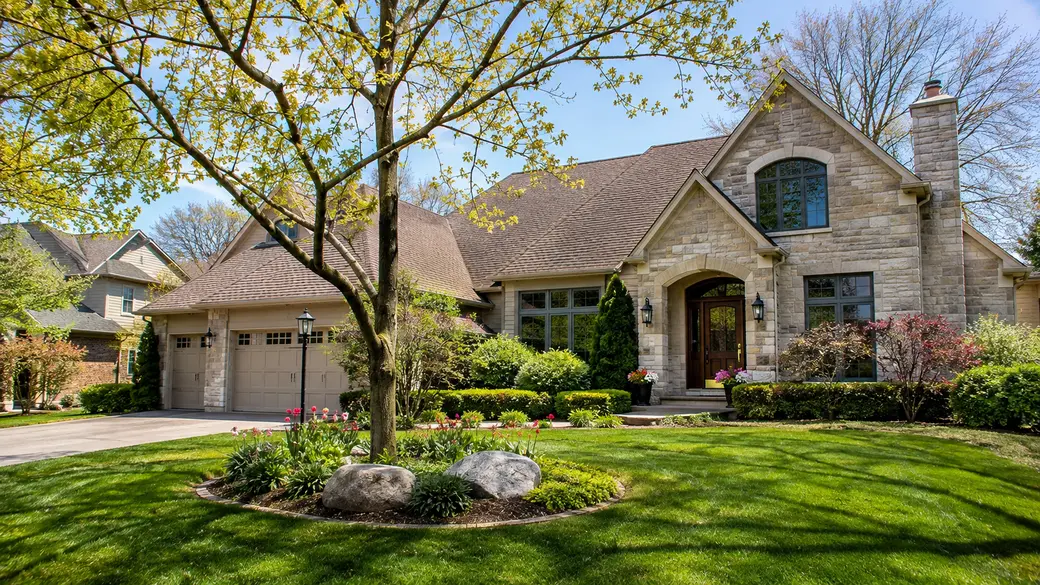
Bloomfield Hills starter-home equity can become the down payment for a larger home, but the amount that matters is your net sale proceeds after the mortgage payoff, selling costs, credits, and any liens. Equity often builds quietly through principal reduction, market appreciation, and well-chosen improvements. This guide explains how to turn that equity into a practical purchase budget while coordinating the sale of your current home with the search for your next one.
Bloomfield Hills Starter-Home Equity Snapshot
A useful equity plan starts with four current inputs: a realistic market-value range for your home, the amount still owed on the mortgage, the estimated costs of selling, and the down payment required for the type of move-up home you want. These figures vary by property condition, financing profile, timing, and buyer demand, so they work best as a coordinated net-proceeds estimate rather than as a single headline number.
For market context, Bloomfield Hills is a city in Oakland County, and Bloomfield Hills mailing addresses extend beyond the city's boundaries. Across those mailing addresses, the reported median sale price was $635,000, and June 2026 sales posted a $643,500 median (ATTOM Data, as of July 2026). Inside city limits, the U.S. Census Bureau's 2020-2024 American Community Survey puts the median owner-occupied home value at $947,900. That spread is a reminder that your own equity depends on the closest comparable homes, not an areawide figure.
How Much Equity Do Bloomfield Hills Starter-Home Owners Have?
Bloomfield Hills starter-home equity is the difference between what your home can realistically sell for and what must be paid from the proceeds at closing. That includes the mortgage payoff, seller-paid costs, negotiated credits, and any recorded obligations attached to the property.
Owners who bought several years ago may have built equity in more than one way. First, the home may be worth more than its original purchase price, although appreciation is never uniform across property types, conditions, and price ranges. Second, each monthly mortgage payment may have reduced the principal balance, even if principal paydown was modest during the earliest years of the loan.
Updates can also influence the sale result when they improve the home's function, condition, or presentation. In Bloomfield Hills, buyers often respond to well-maintained systems, clean and flexible living areas, refreshed kitchens or baths, and strong exterior presentation. Highly personal projects may not return their full cost, but addressing visible maintenance issues can reduce the reasons buyers use to discount an offer.
The practical question is not how much equity appears on paper. It is how much cash may remain after the sale closes. Start by comparing a market-based sale range, a payoff statement good through an estimated closing date, and a complete list of anticipated selling expenses. That turns broad equity into a clearer move-up budget.
Know Your Number Before You List
Get a current market valuation: Base your likely sale range on recent comparable properties, condition, layout, updates, and active competition rather than on an automated estimate alone. A home valuation request is a simple way to start that conversation.
Confirm the mortgage payoff: Request a payoff statement from your loan servicer that reflects the estimated closing date, including accrued interest and any applicable fees.
Subtract selling costs: Include negotiated compensation, transfer taxes, title-related charges, repairs, preparation, and buyer credits when estimating the proceeds available for your next purchase.
Review capital-gains treatment: Eligible primary-home sellers may exclude up to $250,000 of gain, or up to $500,000 for many married couples filing jointly, subject to ownership and use rules in IRS Topic No. 701 (accessed November 2026).
Selling Your Bloomfield Hills Starter Home: Timing and Preparation
The starter-home tier in Bloomfield Hills is generally the more attainable segment of the local market, relative to larger homes, more extensive updates, larger lots, or higher-end features. The exact boundary changes with current inventory and property condition, so a home should be positioned against comparable listings rather than assigned a fixed label based on its prior purchase price.
Preparation can protect the equity you have built. The work that usually matters most is visible and practical: resolving deferred maintenance, improving curb appeal, decluttering, deep cleaning, completing small repairs, and presenting rooms with a clear purpose. Buyers can be especially sensitive to signs that a home will require immediate work after closing, even when the underlying issues are manageable. Because buyers in this tier compare homes closely, pricing a Bloomfield Hills starter home against matched sales protects proceeds as much as preparation does.
Timing should follow readiness, not just the calendar. Spring often brings more buyer activity, but it can also bring more competing listings. A well-prepared home can perform in other seasons when the price, presentation, and launch plan match the active market. Before setting a list date, allow enough time for preparation, photography, marketing, offer negotiation, and coordination with the purchase timeline.
Selling Costs vs. Equity Proceeds: What to Expect in Bloomfield Hills
| Cost category | Typical range or amount for a Bloomfield Hills sale |
|---|---|
| Agent compensation | Negotiated between the seller and brokerage |
| Transfer taxes | Michigan state transfer tax of $3.75 per $500 ($7.50 per $1,000) plus Oakland County transfer tax of $0.55 per $500 ($1.10 per $1,000), subject to statutory exemptions |
| Recording and tax certificate | $30 recording fee per document; $5 Oakland County treasurer's tax certificate for a warranty deed |
| Title and escrow fees | Vary by settlement provider, title work, endorsements, and transaction terms |
| Pre-sale repairs and staging | Depend on condition, scope of work, and presentation plan |
| Mortgage payoff | Outstanding principal, accrued interest through closing, and applicable payoff charges |
| Net equity | Expected sale price minus mortgage payoff, seller costs, negotiated credits, and liens |
On a $635,000 sale, combined state and county transfer tax would total about $5,461 before any exemption. Some sellers of a principal residence may qualify for an exemption from the state portion when the home's state equalized value has not risen above its level at purchase, so it is worth asking the title company to review eligibility.
Michigan law generally makes the seller or grantor legally responsible for the state transfer tax. The parties may agree that the buyer will pay it on the seller's behalf, but that agreement does not change the seller's legal responsibility. Confirm final charges and allocation in the transaction documents. Transfer-tax information: Michigan Department of Treasury and Oakland County Register of Deeds, accessed November 2026.
Bridging the Gap: How to Buy and Sell at the Same Time in Bloomfield Hills
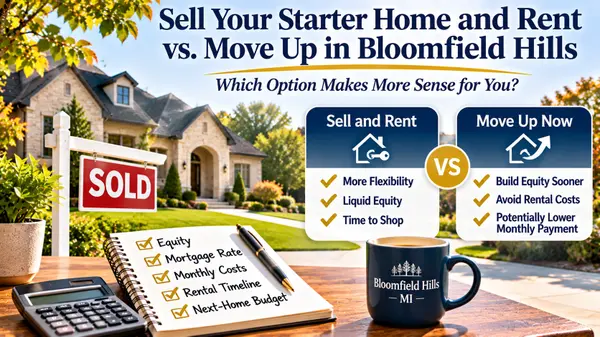
Bloomfield Hills homeowners generally have three ways to coordinate a sale and a move-up purchase: a contingent offer, temporary bridge financing, or selling first and using short-term housing. Each approach manages the same challenge differently: accessing equity without creating an unmanageable timing or payment risk.
A contingent offer makes the purchase conditional on the sale of your current home. It can work well when your property is prepared for the market, priced appropriately, and likely to attract qualified buyers. The trade-off is that a seller may prefer an offer with fewer conditions when several buyers are competing for the same home.
A bridge loan can provide temporary funds for the next down payment before the current home closes. This approach may help when a suitable move-up property becomes available first, but it adds borrowing costs, qualification requirements, and the possibility of overlapping housing payments if the sale takes longer than expected.
Selling first and renting short-term creates the clearest view of your available proceeds because the sale is complete before the next purchase. It can reduce pressure during negotiations, although it may mean moving twice and arranging temporary housing or storage. The tradeoffs of selling first and renting before moving up usually come down to cash flow and how long the search may take.
The right strategy depends on your cash reserves, financing approval, property readiness, and comfort with uncertainty. Review each option against a realistic sale range and a purchase budget that leaves room for timing changes.
The biggest sequencing mistake is using gross sale price as your purchase budget. Use a written net-proceeds estimate before making an offer.
What a Move-Up Home Costs in Bloomfield Hills Right Now
A move-up home in Bloomfield Hills usually means stepping into a higher price tier with more space, additional bedrooms, updated finishes, greater lot privacy, or a layout that better supports a household's next stage. The budget range is shaped by the net proceeds from your current sale, the mortgage amount you qualify for, and the monthly payment you are prepared to carry.
At this level, buyers may find homes with expanded living and entertaining areas, additional bedrooms, attached garages, finished lower levels, dedicated work space, renovated kitchens, or more flexible room configurations. Square footage alone does not determine value. Architectural style, renovation quality, lot characteristics, maintenance history, and location within Bloomfield Hills can all affect the price gap.
The key is to compare the after-sale cash available with the full cost of the next purchase. That includes the down payment, purchase closing costs, moving expenses, reserves, property taxes, insurance, and the payment associated with the remaining loan balance. In Michigan, a home's taxable value uncaps in the year after it sells, so the seller's current tax bill is not a reliable estimate of yours. A mortgage payment calculator can help organize payment scenarios before you select a purchase range.
Starter vs. Move-Up Home: Comparing Buying Power in Bloomfield Hills
The comparison between a starter home and a move-up home is best made through relative buying power rather than a fixed local price threshold. A starter home generally occupies the more attainable portion of the market, while a move-up home commonly offers more space, features, flexibility, or location advantages.
Your net equity determines how much of the move-up purchase can be funded as a down payment. The remaining loan amount, property taxes, insurance, and loan terms determine the monthly payment. Because individual homes vary substantially in condition and features, a side-by-side purchase analysis should compare current listings, estimated sale proceeds, and financing scenarios at the same time.
Financing Your Move-Up: Using Equity as a Down Payment
Net sale proceeds become available after your current home closes, the mortgage is paid off, and seller expenses are deducted. Those funds can then be applied to the down payment and purchase closing costs for the next home. When the sale closes before the purchase, the exact cash amount is known and can be transferred according to the closing instructions.
A 20% down payment is a common conventional-financing benchmark because private mortgage insurance is typically required when the down payment is below that level. It is not the only financing path, but a larger down payment can reduce the loan amount and may reduce or avoid mortgage-insurance costs. The Consumer Financial Protection Bureau's mortgage guidance explains how loan terms, down payment size, and mortgage insurance can affect affordability.
Rates matter as much as equity. The average 30-year fixed mortgage rate was 7.11% as of November 12, 2026, according to Freddie Mac, down from 7.40% in mid-October but still above the 6.24% average a year earlier. On a move-up loan, even a small rate change can shift the monthly payment noticeably, so rerun your numbers when rates move.
Veterans moving up from a home bought with a VA loan should ask a lender about restoring entitlement once the current VA loan is paid off at closing. Restored entitlement can make a no-down-payment VA purchase possible again, which leaves more of your equity available for reserves, updates, or a lower loan balance.
When a buyer needs to act before the sale closes, a bridge loan or home equity line of credit may provide temporary access to funds. Both options require careful planning because they can add interest expense, qualification requirements, and overlapping payment obligations. The central number remains the same throughout the process: expected net proceeds, not gross equity.
Ready to Plan Your Move-Up in Bloomfield Hills?
Danny Dedic leads Dedicated Realty Group, a Michigan-licensed team with eXp Realty, LLC, based in Royal Oak. The team helps Bloomfield Hills homeowners estimate net proceeds with pricing strategy and market analysis, market the current home with professional photography and video, and represent them on the purchase side so both closings line up. They negotiate on your behalf and guide you through inspection, appraisal, title, and closing on each transaction.
For a tailored net-proceeds estimate and sale-to-purchase timeline:
Call or text (586) 855-6672, email: info@dedicatedrealtygroup.com or reach out through the Dedicated Realty Group contact page
Frequently Asked Questions
How much equity do I need to move up to a larger home in Bloomfield Hills?
You need enough net sale proceeds to cover your planned down payment, purchase closing costs, moving expenses, and a reasonable reserve. Calculate that amount by subtracting the mortgage payoff, seller costs, credits, and liens from a realistic expected sale price.
Should I sell my starter home before I buy my next one in Bloomfield Hills?
Selling first gives you a confirmed proceeds figure and avoids the risk of carrying two homes at once. A contingent offer or bridge-financing arrangement can provide more continuity, but each introduces different timing, cost, and negotiation trade-offs.
What are the typical closing costs when selling a home in Bloomfield Hills?
Seller costs may include negotiated brokerage compensation, Michigan transfer taxes, title-related fees, preparation expenses, mortgage payoff, and buyer credits. Combined state and Oakland County transfer tax is $8.60 per $1,000 of the sale price, subject to statutory exemptions, plus a $30 recording fee and a $5 tax certificate fee.
How long does the move-up process take in Bloomfield Hills' current market?
The timeline depends on how quickly the current home can be prepared, marketed, placed under contract, and closed, along with the timing of the next purchase. Build in time for pricing, marketing, negotiations, financing, and coordinated closing dates rather than relying on one fixed schedule.
Will I owe capital gains tax when I sell my starter home in Bloomfield Hills?
Many primary-home sellers may qualify for the gain exclusion described in the IRS rules above if they meet the ownership and use requirements. Prior rental use, previous exclusions, and other facts can affect the result, so confirm the tax treatment with a qualified tax professional.
Categories
Recent Posts
"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "